Sunday, 28 July 2013

Central Banks and Economic Data might weigh on Precious Metals

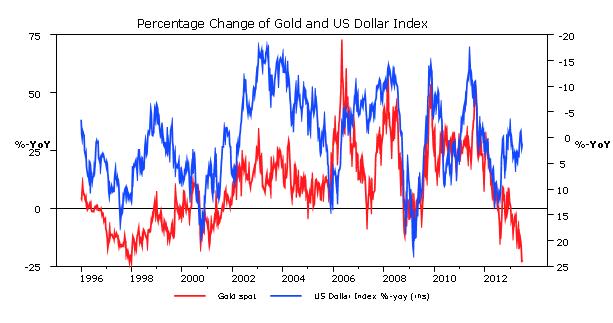
Gold rose further this past week and reached a high at 1,347$/oz. However, it seems that the rise was not driven primarily by the movement of the gold forward rates or the gold lease rates. The 1 month gold forward rate increased from -0.078 to -0.053% while the 1 month gold lease rate came down from 0.269 to 0.240%. Moreover, the major fundamental factor driving gold higher was the US dollar. The US dollar index weakened from 82.623 to 81.656. For the coming week, the US dollar might remain the decisive factor for gold and other precious metals.

The focus in the coming week is on the central bank policy in Europe with the ECB and the Bank of England holding rate setting meetings as well as on the manufacturing PMIs for various countries. And as usual at the first Friday of a new month, the US labor market report will be released.

When the minutes of the latest meeting of the BoE’s monetary policy committee (MPC) had been released, many analysts were disappointed that the MPC decided unanimously to keep the volume of bond holdings unchanged. However, such a result should not come as a surprise. It was the first meeting under the new BoE Governor, Mike Carney. For the two members, who voted for further bond buying, it would not be a wise to oppose the position of the new BoE Governor. Voting with the majority had not changed the result of a vote, but with joining the majority, they demonstrate support for Mr. Carney. Also for Mr. Carney, it was smart to vote with the majority. Voting for more quantitative easing and thus, against the majority, could have been interpreted easily as a defeat damaging his reputation.

However, more important than the actual policy decision was the medium-term guidance, which the BoE gave. Thus, monetary policy remains accommodative, but appears less likely that the MPC will vote next Thursday for further QE measures. The preliminary GDP figures for the second quarter, showing an increase of 0.6% over the first quarter, have reduced the likelihood for further stimulus measures.
At the latest press conference, also the ECB provided the financial markets with a medium-term guidance. ECB president Draghi stated that rates would be at the current or a lower level for an extended period of time. Thus, the kept the door for a further rate cut open. However, also at the forthcoming ECB council meeting a rate cut appears as less likely for two reasons.

First, council members from the Northern Eurozone periphery already opposed a further rate cut at the latest meeting. Their opposition has probably not weakened over the last few weeks. There might be a slight majority in the council for a cut of the key refinancing rate to 0.25%, however, the ECB council is looking for a broad consensus for policy measures. The status quo will probably prevail at least for another month.
Second, the flash estimate of the Eurozone manufacturing PMI shows a reading of 50.1. It is the first time since July 2011 that the manufacturing PMI would be above the critical threshold of 50 if confirmed by the final figure. In Spain, the unemployment rate declined for the first time since 2008, which is another indication that the economic situation in the Eurozone recovers gradually. The ECB always expressed the expectation that the Eurozone economy would improve in the second half of this year. Therefore, it is more likely that the council will take a wait and see attitude and keeps the powder dry.

For the US labor market report, the consensus is looking for a slightly slower pace of new job creation and predicts 180,000 (after 195K in June) additions to the payroll. The unemployment rate is expected to decline to 7.5% from 7.6%. Thus, the percentage of Wall Street economists predicting that the Fed would start tapering the bond purchases at the September FOMC meeting could increase.

For the government bond markets, these developments would be negative. The markets already reacted on the better than expected economic figures in the UK and the Eurozone. However, keeping the monetary policy unchanged by both central banks could dampen hopes for more monetary stimulus further and could lead to another round of bond selling. Whether the yield spread of 10 year US Treasury notes over German Bunds will decline further depends crucially on the US labor market report. A strong report could lead to a renewed spread widening. Higher bond yields are expected to have a negative impact on the precious metals as they imply higher opportunity costs.

The impact on the US dollar is not so clear. Unchanged monetary policy in Europe would be normally negative for the US dollar. However, a strong US labor market report could give the US dollar a push as the market would probably price in a higher likelihood for tapering at the September FOMC meeting. Nevertheless, even with a strong US labor market report, the euro might hold well against the US dollar in the case that the manufacturing PMIs for the Mediterranean countries also improve considerably. Indications for economic improvement, in particular in Spain and Italy, would reduce the credit risk of the government bonds, which should lead to narrower spreads of the German Bunds as the Eurozone benchmark. Of course, the spread tightening could be triggered by selling Bunds and buying Spanish or Italian government bonds. But also investors, which have reduced their exposure in the Eurozone might return as buyers if the economic outlook improves. This could support the euro against the US dollar.


For the precious metals, the US dollar index is more relevant than a single currency pair according to our quantitative fair value models. Thus, a strong US labor market report might be negative for precious metals by leading to a firmer US dollar against the basket of five currencies in the US dollar index. Thus, we expect that gold might end the coming week lower compared to the close of last Friday. But a disappointing US labor market report might push gold above the 1,350$oz level, which is regarded as a resistance level.    

Sunday, 21 July 2013

Dr. Copper moved to China

Copper, which is widely regarded as a leading indicator for economic activity and therefore dubbed as the metal with a PhD in economics, is down 12.5% since the end of 2012. Also other base metals have lost in 2013 so far. All base metals reached their high of the year in mid-February and then moved downwards. Thus, the testimony of Fed Chairman Bernanke, where he indicated the FOMC might taper the bond buying program at one of the next few FOMC meetings, could hardly explain the poor performance of base metals. Institutional investors have sold base metals already before this testimony in May.

In our fair value models, the US dollar index is also one of the explanatory variables for the price development of base metals. As many of the variables are not stationary and also show a seasonal pattern, the year-over-year percentage change had been applied in the models. The strength of the US dollar index following the change of economic policy in Japan (Abenomics) could explain the development of base metal prices to some extent.

When the fair value models were developed, the S&P 500 Index was the stock market index with the best explanatory power among the major stock indices. At this time, China had already risen to the world’s top copper consuming country. However, the S&P 500 index can not explain the decline of base metal prices because the US stock market posted strong gains while base metals moved in opposite direction.

In many reports about the base metal markets, the gradual decline of Chinese GDP growth is often cited as a reason for weaker base metal prices. Therefore, we examined various Chinese macroeconomic variables whether they explain the development of the 3mth LME copper price better than they did before. In order to have enough observation also in the second subsample, the starting date for the second sample had been set to January 2009. However, in 2009 and also for most part of 2010, the development of Chinese leading economic variables and international leading indicators was very similar.

As the interest was only in the explanatory power of some macroeconomic variables for the development of the copper price, we estimated only some bivariate linear regression models instead of multivariate models.

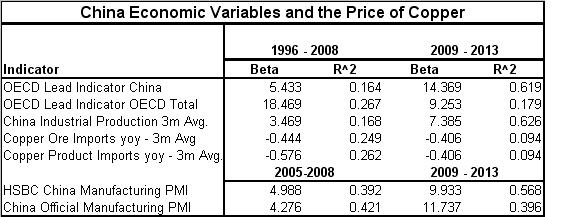
When we developed our fair value models for the base metal prices, the OECD leading indicator for the total OECD explained the development of copper prices better than the OECD leading indicator for China. As shown in the table below, the price changes of copper reacted stronger (higher beta-coefficient) on changes of the leading indicator for the total OECD than on the one for China. Also the R-squared is higher for the OECD region in the estimation period ranging from January 1996 until December 2008.  However, this has reversed in the period following the financial crisis. While the impact of the Chinese leading indicator is now more than 2.6 times higher, the impact of the leading indicator for the OECD region has almost halved. Also striking is the difference in the R-squared. Now, the leading indicator for China could explain more than 60% of the variation of copper prices alone.


A similar development took place for the industrial production in China. As the yoy %-change of Chinese industrial production is very erratic, a 3mth moving average had been applied to smooth the development.

One would assume that Chinese copper imports would play an important role for the copper price. Many analysts had presented charts showing the LME copper price being highly correlated with Chinese copper imports. However, those analysts manipulated the charts in their studies because they showed copper imports in value terms. And it is quite natural that the copper price is highly correlated with the product of copper prices and imported volumes. But looking at Chinese copper imports in volume terms shows a different picture. The regression coefficient for copper ore imports as well as for copper product imports (also smoothed by a 3mth moving average) is negative. A possible explanation for this negative relationship might be that the more copper China imports and then refines, the more the supply of refined copper increases and thus, weighs on the price for refined copper. However, R-squared declined considerably after the financial crisis, which implies that Chinese copper imports contribute less to the explanation of copper price movements.

Manufacturing PMIs for China are only available since mid 2004 for the HSBC index and from 2005 for the official PMI. For both PMIs, the impact on copper prices has risen after the financial crisis and is more than twice the beta coefficient of the first sample period.  But only the HSBC manufacturing PMI contributes more to the explanation of copper price movements.
Chinese macroeconomic variables have a stronger impact on copper prices after the financial crisis than they had before the collapse of Lehmann Brothers. But China was the major copper consuming country also before the financial crisis. Maybe it was the Chinese policy to stimulate the economy and to buy the metal for strategic reserves, which have strengthened the impact of Chinese macroeconomic variables on the movements of the copper price. However, the chart above indicates that the OECD leading indicator for the total OECD region moved most of the time in the same direction as the leading indicator for China. But in the second half of 2012, the leading indicator for the OECD increased, while the Chinese leading indicator headed further down. Therefore, the recovery of copper prices in the yoy-comparison was only short-lived.


Obviously, Dr. Copper moved to China. And there, the metal with a PhD in economics ignores what is going on in the rest of the world. The USA is still the second top copper consumer and the US construction sector is improving further. But this is not reflected in the copper futures the CME where large speculative investors are still holding a net short-position, albeit reduced from 28,048 to 22,380 contracts according to the latest CFTC report on the “Commitment of Traders”. As long as the focus remains only on China, base metals might have only limited recovery potential.

Sunday, 14 July 2013

Negative GOFO – no Harbinger for Rally in Gold

It was the big headline in a market report that gold forward rates (GOFO) were negative for the first time since the collapse of Lehman Brothers in 2008. While this information is correct, it should suggest that this marks again a turning point for the price of gold. While Lehman Brothers went bankrupt on September 15, 2008, it was only 44 days later that gold reached its low at 680$/oz and started the rise to the new all-time high at 1920$/oz on September 6, 2011.  However, the 1month gold forward rate turned negative only in November 2007. The sequence of events is similar this year. Gold reached a new low in late June and then recovered before GOFO rates turned negative. But the similarities end here.

Negative GOFO rates imply that spot gold with delivery after 2 business days is trading higher than the price for gold fixed today for delivery in 1, 2, 3 or 6 months. The 1 year gold forward rate remained positive last week. Thus, the gold market turned from contango (the normal state in this market) into backwardation, which is unusual for the precious metals. In other commodity markets, backwardation is often explained by the concept of convenience yield. However, this concept does not apply for gold and silver as there is an active market for lending these two precious metals. Moreover, gold forward rates can not form freely in the market. They are bound by money market interest rates and the lease rates in the market for lending gold. Arbitrage could set in, if the following identity equation is violated:

            Gold forward rate = money market rate – gold lease rate.

The money market rate is normally the US dollar LIBOR for the corresponding duration of the gold forward.

This identity equation also helps to explain why the gold forward rate turns negative. Either the LIBOR rate has to fall or the gold lease rate has to increase or there is a combination of both factors.

In 2008, immediately with the collapse of Lehman Brothers, the 1mth gold forward rate increased as the LIBOR rate, which includes bank risk, rose stronger than the gold lease rate. However, already at the end of September, the forward rate reached its peak and turned around. This was triggered by a jump in the gold lease rate. But from the middle of October, both rates fell. Due to the Fed policy, the LIBOR rate fell stronger than the gold lease rate, which remained above 1.25%. The 1mth LIBOR was briefly below the gold lease rate in November 2008, which caused the negative gold forward rate.  

However, in 2013, the 1mth LIBOR rate showed a downward bias, but the overall range was just less than 2 basis points. This is not enough to explain the negative gold forward rate of -0.11% on Wednesday. Thus, unlike in 2008, the movement of the gold lease rates was the responsible factor for the backwardation in the gold market.

The crucial question is thus, which factors drive the gold lease rate. Our quantitative research identified two factors, which explain around 85% of the movements of the 1mth gold lease rate since January 2012, the price of gold and the gold inventories in CME warehouses. The chart above shows the weekly gold lease rate and the spot gold price. It is obvious that the gold lease rate also started to increase when gold resumed its downward move leading to the low in late June. Hedge funds not only sold physical gold they held via ETFs but also sold gold short in the physical market. As those deals usually have to be settled after 2 business days, the hedge funds have to lend the gold from institutional holders. This demand already led to a steady increase of the lease rate.

The next chart shows the development of the gold stocks held in CME warehouses together with the gold lease rate and the model estimate of the lease rate. As long as the inventories are abandoned, hedge funds being short physical gold don’t have to worry about covering their shorts. They could meet the obligation to return the gold lend by buying in the spot market or by purchasing futures with expiration before they have to make delivery. Then, they can take physical delivery from the long future and meet their obligation to return the gold back to the lender. However, if inventories fall rapidly, the risk increases for the borrower to obtain gold right in time by purchasing a gold future and take delivery. But also the risk for the lender increases that the gold will be returned at the agreed date. Thus, lenders get hesitant to enter new lease agreements and/or demand higher risk premiums for lending gold.


After the speech of Fed chairman Bernanke last Wednesday, following the release of the FOMC minutes, the gold lease rates came down. As an immediate tapering of the bond purchasing program got less likely, also the short speculation against gold declined, which contributed to the decline of the lease rates. The US dollar weakened against the major currencies and also the bond markets recovered. However, it remains only a question of timing that the Fed will reduce the volume of being bonds. Thus, the medium-term outlook for a firmer US dollar against the major currency remains intact. Therefore, the upside potential for gold appears to be limited and the negative gold lease rate is in no way a harbinger for a rally in the gold market like after the collapse of Lehman Brothers. On the other hand, as long as gold inventories held in CME warehouses decline, the risk for selling gold short increases. This might limit also the downside risk for the gold price. However, all in all, the risk for gold appears to be more biased to the downside despite the recovery last week.

Sunday, 7 July 2013

It is only the Fed

The slogan “it is the economy, stupid” is attributed to Bill Clinton’s first presidential election campaign. For many market participants, today’s version had to be “it is only the Fed, stupid”.

There is much discussion, especially in Germany about the independence of the ECB. However, this discussion centers on independence from fiscal policies of the eurozone member countries. But even the head of the German Bundesbank, Mr. Weidman, the strongest opponent of OMT on the fear the ECB would lose it independence, never regarded the ECB monetary policy as being dictated by the FOMC. However, this had been a widespread believe in financial markets.

The best example for this unjustified believe were the comments from some traders quoted by ThomsonReuters after the release of the final figures of the PMI for the eurozone and some member countries. As the PMI was slightly stronger than expected, bonds and stocks had been sold on expectations that the ECB would end it expansionary monetary policy soon (see also comment from Monday, July 1, 2013).  But the eurozone is still in a recession and GDP growth forecasts for the strongest economy, Germany, had been revised lower lately by some institutions to a mere +0.3% in this year.

Unlike the Fed, the ECB has only a single mandate of maintaining price stability. The ECB’s inflation target is to keep harmonized CPI inflation close to but below 2% in the medium-term. This allows even for some temporary overshooting of the target as long as the medium term inflation outlook remains well anchored. But in a recessionary economic environment, there is little underlying inflation risk. Thus, it is not rational expecting the ECB to end the expansionary monetary policy only because some PMI figures approach the 50 threshold.

Despite earlier comments from ECB president Draghi, financial markets remained in irrational mode. This induced the ECB council to send another clear message to financial markets. Breaking with the tradition of stating that the ECB council is not pre-committed, the ECB council stated that the key interest rates will stay at the current or lower level for an extended period of time. But unlike the Fed, the ECB gave no clear guidance how long this extended period will last. Questions during the press conference about the duration were only answered by Mr. Draghi as “not 6 month, not 12 months, but by an extended period”.

Similarly, it was also not rational to expect the BoE to end expansionary monetary policy anytime soon. The MPC did not embark on another round of bond purchases, but also did not send any indication there might be a shift towards a restrictive policy. Thus, whether the statement made by the BoE governor Carney was driven primarily by the change at the helm of the institution or by the irrationality of financial markets is of minor importance.  What counts is the message itself that monetary policy remains accommodative.

In the US, the labor market report has been seen as another indication that tapering the bond buying program by the Fed would be imminent. Two major banks, Goldman-Sachs and JP Morgan, now have revised their forecast and also expect the FOMC to announce at the September meeting to reduce the volume of monthly bond purchases. From our point of view, the labor market report was a good one, but not one pointing to any urge for the FOMC to scale down QE3.

The FOMC statements always refer to the unemployment rate as the second target and not to the non-farm payroll figure. Of course, a high number of newly created jobs month after month are one important factor for reducing the unemployment rate. But another important factor is the development of the civilian workforce. In the second quarter, the workforce increased by more than 800K to 155,835 thousand persons. In the quarters before, the workforce declined as many persons unable to find a job left the workforce. With the improved economic outlook, some of those leavers return again. This was the reason that the unemployment rate remained unchanged at 7.6% despite more new jobs than predicted had been created. It has to be expected that the increase of the workforce is going to continue. This return to the workforce is dampening the decline of the unemployment rate. But if the unemployment rate remains at the current level, it gets less likely that the FOMC will vote for reducing the volume of QE3. Whether job creation will be sufficiently strong to reduce the unemployment rate over the summer months has to be seen. But that the Fed enters tapering in September is not yet a done deal.

Thus, the outlook for monetary policy is divergence in the direction. In Japan, the target is to reach a CPI inflation of 2% within 2 years, which requires the BoJ to increase its balance sheet. The ECB and the BoE will remain expansionary of still some time. Only the Fed has currently an exit plan, but his plan is data dependent, but will not lead to an increase of interest rate target. Therefore, there should be little movement in short-term interest rates. It should then be the long-term government bond yields, which drive the movement of foreign exchange rates.

After the release of the US labor market report, the yield on the 10yr US T-notes jumped from 2.52% before the Independence Day to 2.74%. The spread over 10yr German Bunds widened from 85 to 104 basis points. Weakness in the US Treasury market is also pulling the yields on other safe haven government bonds higher, but not at the same magnitude. Thus, the spreads are widening and lead to a firmer US dollar.

At the current level, 10yr US Treasury notes start to get attractive for carry-trades. However, for financial institutions to enter such trades, also the upside risk has to be limited. This is at present not the case, as the uncertainty in the US Treasury market is likely to stay until the FOMC has made a clear decision and does not only lay out the road map. Thus, we still expect that yields on 10yr US Treasury notes could rise towards 3% before stronger entering of carry trades sets in. This implies that the US dollar could strengthen further against other major currencies.

Last week, we pointed out that the negative link between precious metals prices and the US dollar index remain well intact, but that the regression coefficients between precious metals and the S&P index as well as the US Treasury yield had reversed and became negative. Thus, a further rise of US Treasury yields is likely to exercise two negative impacts on the performance of precious metals, one directly and indirectly via the foreign exchange markets and a rising US Dollar index. Thus, also the third quarter, which just started, appears to be a negative on for the precious metals.


Monday, 1 July 2013

Darwin and Financial Markets

Darwin’s evolution theory states that the strongest species survive. This has also become knows as “survival of the fittest”. However, this appears not to be the case in financial markets. Here the cheapest and not the smartest staff members of financial institutions appear to have survived the financial crisis. The most recent example is delivered by comments from traders following the release of the PMI data for the eurozone and member countries on July 1st, 2013.

The final PMI came in slightly above the flash estimate and the consensus forecast for the eurozone at 48.8, which was one tenth of a percentage point above the consensus. European stock markets, turned negative after being in the plus before the data release. Within 20 minutes, the DAX index lost 0.9% compared to the preceding close. Reuters reported “European shares turned negative on Monday after euro zone manufacturing activity showed signs of stabilisation last month, which traders said sparked concerns of tightening of European Central Bank monetary policy.”

This is ridiculous! Only last week, ECB president Draghi indicated that the ECB has still room to maneuver, which implies that the ECB could cut rates further. Leading European economists polled by a German business daily recommend lowering the key refinancing rate further to 0.25% at the ECB council meeting later this week.

Furthermore, the eurozone PMI is still below the 50 threshold, which is widely regarded as the threshold between contraction and expansion. Thus, the improvement of the PMI is just an indication that the eurozone might come out of the recession later this year. The capacity utilization in the eurozone is far from pointing to any inflationary pressure. The situation in the labor market is dismal in many countries of the eurozone, especially in the South. Therefore, any improvement of the economic situation is currently highly welcomed by the ECB and not a reason of concern.

Also price stability, the ECB’s main target, is not endangered. The flash estimate of the June harmonized CPI inflation in the eurozone edged up from 1.4% to 1.6%. However, this reading is still comfortably below the upper level of the ECB inflation target. Furthermore, the pick-up of the inflation rate is attributable to seasonal food prices, which is not a reason to tighten monetary policy.


Thus, fearing the ECB might tighten monetary policy any time soon is rather insane. It appears that some traders reacted more like skinner rats instead of using their brains. 

Sunday, 30 June 2013

Performance of Precious Metals in 2013

Most analysts polled by the London Bullion Market Association at the start of 2013 were optimistic for precious metals in 2013. They predicted annual average prices to be higher for another year. However, after the first half of 2013 is over, it looks rather unlikely that average prices in this year will be above the average price of 2012.

The table below shows the spot price of the four precious metals as well as the percentage change over the end of the previous end of quarter and also the percentage change in the first half. The development of gold and silver in the first quarter of 2013 could still be interpreted as a correction after the end of the festival season, which is not uncommon. Platinum and palladium moved higher due to the development in South Africa and fears of supply shortage. But the second quarter had been a disaster for all precious metals.  


Based on our quantitative fair value model for gold, we investigate whether this plunge of precious metals in Q3 could be explained by the major fundamental factors driving the price of gold. Our model is based on weekly data. As also financial and commodity markets show seasonal influences, we did not use weekly, but annual percentage changes. Thus, there was no need to include also further seasonal adjustments in the model equations. All fundamental factors were included in the equations for the four precious metals. These factors are the 1) the US dollar Index, 2) the price of crude oil (WTI), 3) the S&P 500 composite index, 4) the yield on 10yr US Treasuries and the net long position of non-commercials in the futures traded at the Comex division of the Chicago Mercantile Exchange (CME). For the US Treasury yield, instead of percentage changes, the absolute yoy-change in basis points had been used. The net-long position has been divided by 1000.

Linear regression models based on time series of financial asset or commodity prices often lead to residuals, which are serially correlated. Therefore, the models include a first order autoregressive term for the residuals and the parameters for the exogenous fundamental factors and the autoregressive error term have been estimated simultaneously. The model was first developed in 2006, and therefore, data from January 1997 until September 2006 was used in the estimation. The regression coefficients are all significant at the 5% level and have the expected sign.

The following chart shows the development of the yoy percentage change of the spot gold price and the estimated values. At a first glance, the model appears to predict the development of the gold price still quite well. However, this good fit could be the result of the autoregressive error term, which might deviate further away from the fair value instead of oscillating around it.

Since the end of 2012, the yoy percentage change of gold dropped from 2.47 to -22.07% at the end of June 2013, which is a change of 24.54 percentage points. Thus, we investigated how much the five fundamental factors contributed to the dismal performance of gold. The US dollar index firmed on the strength of the US dollar against the Japanese Yen and thus contributed a -0.64 percentage points. Also the drop of the net-long positions held by the large speculators contributed with -2.15 percentage points to the negative performance of gold. However, crude oil, the S&P 500 index and the yield on the 10year US Treasury notes all made a positive contribution. In total, the five fundamental factors indicated that gold should have shown a decline of the yoy percentage change by 0.92 points to 1.55% instead of falling to -22.07%.  

This already indicates there must have been a structural change in the precious metals markets. Relationships collapsed, which held before the financial crisis and even in the first few years after the crisis.

One possible reason for a structural change might have been the speech by ECB president Draghi held in July 2012 in London, where he pledged to do everything necessary to keep the euro intact and announced what later became known as OMT.  A second reason might have been the introduction of Abenomics in Japan in the final quarter of 2012. Thus, the regression coefficients have been estimated again, but based on data from July 2012 until the end of June this year. Most of the variables or lag structures are no longer significant at the 5% level. Only the US dollar index and the S&P 500 index remained significant factors. However, the regression coefficient of the S&P index increased and changed the sign from positive to negative.

Slight modifications of the lag-structure led to a model, where the five fundamental factors are significant again. However, now also the regression coefficient for the annual change in the 10year US Treasury yield changed sign and magnitude. Rising yields, which had earlier been interpreted as a sign of rising inflation rates, are no longer positive for gold. They now lead to falling gold prices, which reflect the fear that an end of QE would eliminate any reason for holding gold.

Crude oil was the only one of the five factors, which made a positive contribution of 4.75 percentage points. The US dollar and the S&P 500 index both contributed less than one percentage point to the decline. The rise of the 10year US Treasury yield contributed -6.7 percentage points. The fall of the net-long position held by large speculators had the strongest negative impact on gold’s negative performance with -8.75 percentage points. All in all, according to the adjusted and re-estimated model the five fundamental factors contributed -12.45 percentage points to the fall of the yoy percentage change of the gold price in the first half of 2013.

The chart above shows the development of the yoy percentage change of the gold price and the estimate based on the adjusted model fitted for the period from July 2012 until June 2013.  It is obvious, that a good fit is only obtained for the period from early 2012 onwards. For the time before, the fit is worse. This clearly indicates that the structure of the gold market has changed last year.


It is uncertain, how long the US stock market and the US Treasury yield will have a negative impact on the development of the gold price performance. However, even if the regression coefficients of the adjusted model remain valid beyond the estimation period, the fundamental factors explained only 12.45 of the 24.54 percentage point drop in the yoy gold price change. Thus, almost half of the plunge could not be explained by the major fundamental factors of the model. This implies that gold overshoot on the downside. If the fundamentals don’t deteriorate further, there is some potential for a recovery. But the sentiment in the gold market is seriously damaged and the famous knife is still falling. Thus, it appears too early to try catching the knife now.

Sunday, 23 June 2013

The Fed and selective information bias in markets

Many academic theories rely on the assumption that markets were information efficient. However, this assumption appears to be proven false in reality again and again. Reactions in financial and commodity markets after the release of the FOMC statement on June 19, 2013 provide the latest example. Moreover, the developments support more the thesis of behavioral finance that there are selective information biases among traders and investors.

For the time being, the Fed continues its bond purchasing program with an unchanged total volume of $85bn. However, the FOMC statement also pointed out that “the Committee is prepared to increase or reduce the pace of its purchases to maintain appropriate policy accommodation as the outlook for the labor market or inflation changes”. This already indicates that the FOMC would also be ready to increase the volume of bond purchases again after tapering the volume if incoming economic data were suggesting a slower economic pace than expected. During the press conference, Fed chairman Bernanke explained the possible path of reducing step by step the volume of bond purchases. The FOMC might start later this year and end the program completely by the middle of next year.

However, the markets obviously totally overheard the conditions attached to this possible schedule. This scenario outlined depends on the condition that economic data coming in has to confirm the projections of the FOMC. Also during the press conference, Mr. Bernanke pointed out that the volume of QE3 could be increased again if the economic development is less favorable.

Many commentators stated that tapering the bond buying program would be the end of expansionary monetary policy. This is absolute nonsense for several reasons. First, even if the FOMC will reduce the volume of bond purchases as outlined by Fed chairman Bernanke during the press conference, the Fed will still increase the amount of bonds held until mid-2014. Second, an end of monetary expansion is usually defined as a shift in policy towards a restrictive regime. However, holding a constant amount of bonds by the Fed does not imply that policy gets restrictive. The Fed policy might only become less expansionary. Taking the foot from the gas pedal does not mean to step immediately on the brake!

Third, an end of unconventional ways to provide liquidity to the financial system does not imply that the conventional ones would be closed too. Financial institutions having access to the Fed could still obtain funds by borrowing from the Fed. The yields on medium- to long-term US Treasury bonds have still some upside potential. But the steeper the yield curve gets, the more attractive will be the risk/return profile of carry-trades. Banks could then buy US Treasury paper, which will be refunded by repo operations with the Fed. Thus, banks might even compensate the decline of demand for Treasury and mortgage bonds by the Fed.

An end of expansionary monetary policy furthermore requires that the FOMC would increase the Fed Funds target rate. Again, the FOMC statement does not provide any hint that this would be the case any time soon. The FOMC stated “the Committee decided to keep the target range for the federal funds rate at 0 to 1/4 percent and currently anticipates that this exceptionally low range for the federal funds rate will be appropriate at least as long as the unemployment rate remains above 6-1/2 percent,…”. According to the projections, only three members expect a rate hike in 2014, while the broad majority expects the first rate hike in 2015.

The development of the US unemployment rate remains the key for the further direction of the Fed policy. During the months of falling unemployment rate, the bond bulls argued that the decline was only due to people leaving the workforce as conditions to find a job were hard. We always argued that this is a normal movement, which will reverse once conditions improve. The labor market figures released earlier this month indicate that this turning point might have been reached. Thus, the unemployment rate might decline at a slower pace than the consensus at Wall Street expects due to persons returning back to the workforce. But in this case, the monetary policy of the Fed is likely to remain expansionary longer than the market currently prices in.

The Fed Funds futures at the CME discount a hike of the Fed Funds target rate already by December 2014 with a probability of more than 50%. Thus, the market is far ahead of the Fed and probably will have to revise its expectations down again.

If the major buyer in a market declares that he will reduce his purchases, the normal reaction is that prices decline. Therefore, the rise of medium- and long-term US Treasury yields is justified. Thus, the crucial question is, how far will yields rise.  A good starting point is to look at the spread of the 10yr US Treasury yield over the 3M T-Bill rate or the 3M US Dollar Libor rate. Currently this spread is at 250 and 227 basis points, which is well above the mean of monthly data since January 1984. However, both spreads are less than 1 standard deviation above their respective mean. Thus, the spread still has some upside potential. But on the other hand, it is also less likely that the spreads would move deep into the extreme zone, which was normally reached after a period of strong growth and a shift towards a restrictive monetary policy. Therefore, a yield on the 10yr US Treasury note at 2.75% could already be a buying opportunity and close to 3.0% a strong one.

The reaction in the stock and commodity markets following the FOMC statement and the press conference by Fed chairman Bernanke are not justified. First, as shown above, the tapering of the bond buying program later this year does not constitute an end of an expansionary monetary policy. Furthermore, reducing the volume depends on economic growth and a decline of the unemployment rate. Both factors are normally positive for company profits and thus also for the stock market. Second, the yield spread is one of the best indicators for the stock market. A rising yield spread is usually leading to a higher yoy-change of the S&P 500 index. Since 1985, the percentage change of the S&P 500 index one year later was 3.5 times the spread (in percentage points) between the yield on 10yr US Treasury notes and 3m T-Bills. Thus, the spread widening should normally be positive for the stock markets going forward.

All in all, we come to the conclusion, that the market was very selective in interpreting the message send by the FOMC and Fed chairman Bernanke. Besides neglecting some of the information presented, the market also did not interpret the message correctly. Tapering the bond buying program is not the end of expansionary monetary policy. US President Franklin D. Roosevelt stated in his first Inaugural Address “the only thing we have to fear is fear itself”. However, the markets wanted to be fearful. Warren Buffet’s advice to be fearful when others are greedy and greedy when others are fearful might be invaluable again currently.